

Cherry: The Smarter Way to Pay analysis by Appwee
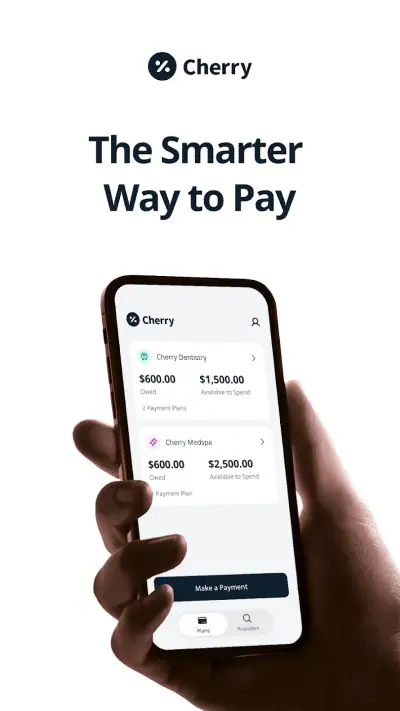
I tested Cherry: The Smarter Way to Pay as a finance app with a very specific purpose: helping people manage payment plans and keep up with scheduled payments. That focus makes it easier to understand than a broad budgeting app, but it also means the experience depends heavily on whether your financial routine actually includes plans that need organizing. I would not treat it as a complete replacement for banking, budgeting, or expense-tracking tools. I see it more as a focused companion for keeping payment commitments visible and manageable.
The app is free, carries an Everyone age rating, and comes from Cherry Technologies, Inc. It has reached over one hundred thousand installs and holds a 4.5 average from more than one hundred ratings, with around fifty written reviews. Those figures suggest that it has found a real audience, although I would still judge it by how well its payment-plan approach matches my needs rather than by popularity alone.
How Cherry fits into a shared household
The most useful household scenario is a couple or family member trying to coordinate a planned purchase without relying on scattered messages, paper reminders, or memory. Imagine one person arranging a payment plan while another person helps keep the household budget on track. In that situation, Cherry can serve as the place to check what needs attention and when, while the household’s main bank account remains the source of truth for available money.
That distinction matters. I would not assume that installing the app on a shared tablet turns it into a family finance hub. A shared device can make information easier to access, but it can also blur who is responsible for an account, a payment, or a change to a plan. Before using it together, I would agree on one simple rule: one person owns the account and confirms the payment details, while others use the app only to coordinate around that information.
For a household, the strongest benefit is reduced ambiguity. Instead of asking, “Did we already deal with that payment?” I can open the app and review the plans I am managing. That is a small improvement, but small improvements are valuable when several recurring obligations compete for attention. The app’s central idea is practical because it addresses a specific point of stress rather than trying to become an entire financial control center.
There is also a useful trade-off here. A shared device may be convenient, but convenience should not be confused with shared ownership. If two adults need separate financial responsibilities, I would keep their accounts and payment decisions separate and use conversation to coordinate. Cherry may help one person manage plans, but I would not build a household process around casually passing one signed-in device from person to person.
What I would do before the first payment plan
My first step would be to decide what I expect Cherry to handle. If I want a complete view of income, spending categories, savings goals, and bank balances, this is probably not the right starting point. If my immediate problem is remembering and organizing payment-plan obligations, its narrower focus is more appealing. Defining that boundary prevents disappointment later.
I would also set up the app when I have the relevant payment information nearby, rather than while rushing through a purchase. A calm setup makes it easier to check the plan terms, identify the responsible person, and compare the schedule with the household budget. The most important practical tip is to treat the app as an organizer for commitments, not as permission to spend more than the household can comfortably afford.
On a shared phone or tablet, I would pay attention to account boundaries from the beginning. I would avoid leaving the app open where another person could accidentally review or alter financial information. Even in a trusted household, a clean separation between the account holder and other users reduces mistakes. Children, guests, or a partner who is only helping with reminders should not automatically be treated as account administrators.
That approach is especially important because the Everyone rating describes the app’s general age suitability, not a guarantee that every financial decision is appropriate for a child. I would be comfortable explaining the idea of a payment schedule to an older child as part of a supervised money lesson, but I would keep actual account access and payment responsibility with an adult. The age label should not replace judgment about maturity, privacy, or financial authority.
Keeping responsibilities clear after setup
Once a plan is active, coordination becomes more useful than constant checking. I would review upcoming obligations at a regular household moment, such as when planning the month’s bills, then discuss anything that could affect the budget. This is better than opening the app repeatedly without making a decision. The app can show what needs attention; the household still needs a clear agreement about who will act.
A practical workflow is to pair each plan with a real-world responsibility. One person checks the schedule, another confirms that the household account can cover it, and the account holder completes the payment action. That division avoids the common problem where everyone assumes somebody else handled the task. It also makes Cherry more useful in a shared setting without pretending that the app itself manages family communication.
I would keep a small written or digital note beside the app for context that may not belong in a payment-plan view: why the purchase was made, which household budget covers it, and what to do if income changes. This is one of the less obvious ways to use the app well. A payment schedule tells me when an obligation exists, but a household note explains how the family intends to absorb it.
Another worthwhile habit is checking the plan against the bank account before committing to unrelated spending. A scheduled payment can look manageable in isolation and still create pressure when combined with rent, utilities, subscriptions, and groceries. Cherry is most helpful when it prompts a broader conversation rather than encouraging me to focus only on the next installment.
Trust, privacy, and the age question
Finance apps require a higher level of trust than ordinary reminder tools. I would want the person using Cherry to understand which information is personal, which actions affect money, and which details should not be shared casually. On a household device, I would use a separate device profile or a clear sign-out routine if the operating system supports it, rather than assuming that family familiarity makes privacy irrelevant.
The app is listed as free, which removes a direct purchase barrier for trying it. That makes it easier to test whether the workflow suits the household before changing established habits. Still, “free” does not mean that financial decisions become risk-free. I would read every payment detail carefully and avoid authorizing anything simply because the app makes the process feel organized.
For teenagers, Cherry could be introduced as a supervised way to discuss planned payments, timing, and responsibility. I would not hand over an adult’s account for casual exploration. A young person may understand the interface without understanding the consequences of a missed payment or an overextended budget. The right role is educational and supervised, with the adult retaining control of the actual financial commitment.
For older relatives, the appeal may be simplicity rather than collaboration. If someone finds multiple banking screens confusing, a focused view of payment plans could be easier to discuss. I would still confirm important details verbally and avoid making the app the only record of a financial obligation. A second person can help with coordination, but that should happen with the account holder’s permission and awareness.
Where Cherry is better than ordinary alternatives
Compared with a spreadsheet, Cherry should feel more purpose-built for someone whose main concern is managing plans and paying according to a schedule. A spreadsheet can be flexible, but it requires manual structure, consistent formatting, and regular maintenance. I would choose the app when I want a dedicated place for this task instead of building my own columns, formulas, and reminders.
Compared with a general budgeting app, Cherry’s narrower purpose may be an advantage. Broad budgeting tools can show spending patterns and categories, but they may make a specific payment plan feel like just another transaction. Here, the plan itself is the focus. That can make it easier to discuss one obligation with a partner without opening an entire household spending history.
On the other hand, a banking app remains the better option for checking balances, confirming completed transactions, and managing the account from which money is paid. I would use Cherry alongside a bank rather than instead of one. If my needs are primarily account security, transfers, statements, or full transaction history, the bank’s own app is the more appropriate tool.
A calendar or reminder app may still be enough for someone with only one simple obligation. Cherry becomes more compelling when payment plans are important enough to deserve their own organized workflow. The trade-off is specialization: it can reduce clutter for plan management, but it will not necessarily replace every tool I already use for personal finance.
Small friction points that affect the decision
The first limitation is scope. The store summary presents Cherry as a way to manage plans and pay on a schedule, and that tells me exactly where to keep expectations. I would not download it expecting investment tracking, detailed spending analysis, shared family budgets, or a complete financial dashboard. Someone looking for those functions should start with a broader finance solution.
The second limitation is human coordination. An app cannot resolve a disagreement about who should pay, whether a purchase is affordable, or what happens when circumstances change. In a shared household, the quality of the result depends on the agreement around the app. Without that agreement, even a clear schedule can become another source of confusion.
The third is that a focused payment tool may encourage tunnel vision if I use it carelessly. Seeing an organized plan can make an obligation feel more manageable than it really is. My advice is to review the household’s total commitments before adding another plan, especially when several payments fall in the same period. The app should support restraint, not merely make borrowing or deferred payment feel smoother.
I would also give myself time to learn the workflow instead of judging it after one glance. The current version is 1.3.0, and the app was released on February 20, 2026, so I would expect the experience to be relatively early in its public life. That is not a criticism by itself, but it is a reason to keep my process simple and maintain a backup awareness of important payment dates while I become comfortable with it.
Who should use it, and who should skip it
I think Cherry is a good match for an adult who regularly deals with payment plans and wants a focused way to keep those commitments organized. It is also worth considering for a couple that needs a shared conversation point but does not want to combine every aspect of their finances. The free price makes experimentation straightforward, and the Everyone rating makes the app broadly accessible as software, provided financial access remains appropriately supervised.
I would skip it if my finances are already easy to manage through one bank app and a single reminder. Adding another tool can create duplication rather than clarity. I would also look elsewhere if I need detailed household budgeting, automatic categorization, investment information, or a fully shared multi-person finance system. In those cases, a dedicated budgeting platform or the bank’s own tools may fit better.
People who dislike maintaining more than one financial workflow should be especially selective. Cherry makes sense when its plan-centered view solves a real problem. If I have to copy the same information into several apps, the extra organization may not be worth the effort. The best test is simple: after using it for a short period, can I answer what is due, who is responsible, and whether the household is prepared without opening several unrelated tools?
My household verdict
My overall impression is that Cherry is most valuable when I treat it as a focused payment-plan companion rather than a universal money manager. Its purpose is easy to explain, and that clarity can help a household move from vague reminders to a more deliberate routine. I especially like the idea of using it to support a monthly check-in, where one person reviews the plans and the household discusses the budget around them.
The app does not remove the need for judgment, privacy, or communication. On a shared device, I would keep account ownership clear, limit access to the responsible adult, and use the app as a coordination aid rather than a substitute for trust. For younger users, I would make it part of a supervised conversation about money, not an open invitation to manage real payment commitments.
If your main challenge is keeping scheduled plans visible, Cherry is worth trying because it stays centered on that job. If your challenge is understanding every part of your financial life, I would choose a broader alternative and possibly use Cherry only if payment plans remain difficult to track. In my experience, that honest division of roles is what makes the app useful: it works best when it simplifies one important responsibility without pretending to replace the rest of your financial system.
Gallery
Cherry: The Smarter Way to Pay Pros and Cons
- Splits eligible purchases into manageable installments.
- Clear repayment schedule helps users plan monthly expenses.
- May offer a quick checkout experience with supported retailers.
- Useful for spreading the cost of larger everyday purchases.
- Can help avoid using a traditional credit card for some purchases.
- Approval and spending limits may vary by user and transaction.
- Late payments could lead to fees or affect your credit profile.
- Not every retailer or purchase category may be supported.
- Installment plans can make overspending easier to overlook.
- Terms
- fees
- and eligibility should be checked before accepting an offer.
Cherry: The Smarter Way to Pay Frequently Asked Questions
What is Cherry: The Smarter Way to Pay?
Cherry is a financing and payment platform that allows eligible customers to split the cost of products or services into scheduled installments instead of paying the full amount upfront. It is commonly offered by participating merchants, particularly in areas such as healthcare, wellness, beauty, and elective services. Available payment plans, loan terms, and approval requirements can vary depending on the merchant and the customer’s application.
How does the Cherry payment application process work?
To use Cherry, you generally begin through a participating merchant or the Cherry platform, provide the requested personal and financial information, and submit an application for review. If approved, you can review the available payment plan before accepting it. The application may involve identity verification and a credit assessment, so approval is not guaranteed. Carefully check the repayment schedule, total cost, and any applicable terms before proceeding.
Does using Cherry affect my credit score?
Cherry may perform a credit check when evaluating a financing application, and the type of inquiry or reporting can depend on the specific product, lender, and application stage. A prequalification step may not always have the same effect as formally accepting financing, but users should not assume that every check is impact-free. Read the disclosures shown during the application and contact Cherry or the financing provider if you need clarification.
Are there fees or interest charges when paying with Cherry?
The cost of using Cherry depends on the payment plan you are offered. Some plans may advertise promotional or low-interest financing, while others can include interest, finance charges, late fees, or other costs. The exact annual percentage rate, repayment amount, number of installments, and total amount payable should be displayed before you accept an offer. Review these details carefully rather than relying only on the advertised monthly payment.
What should I do if I miss a Cherry payment or need a refund?
If you expect to miss a payment, contact Cherry and the participating merchant as soon as possible instead of waiting for the account to become overdue. Late payments may result in additional charges or other consequences under your agreement. Refunds, cancellations, and disputes often involve both the merchant and the financing provider, so keep receipts and written confirmations. The app or support center may also provide account-management and repayment assistance options.














